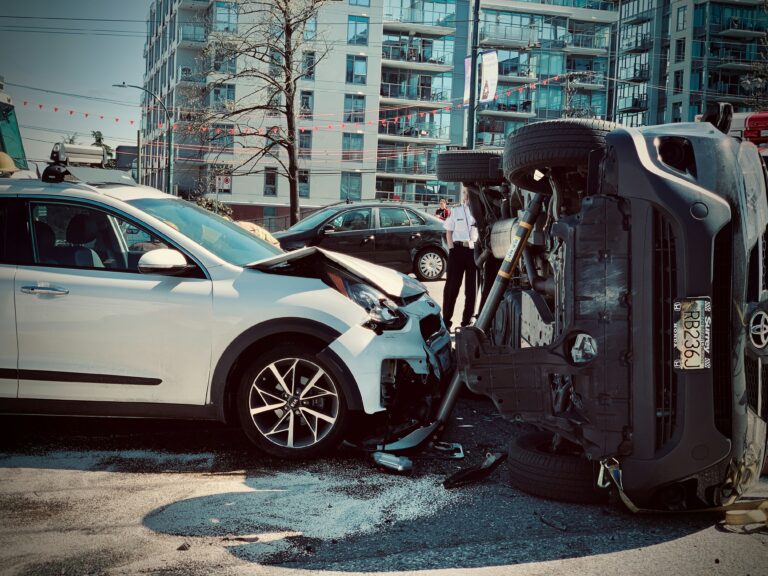
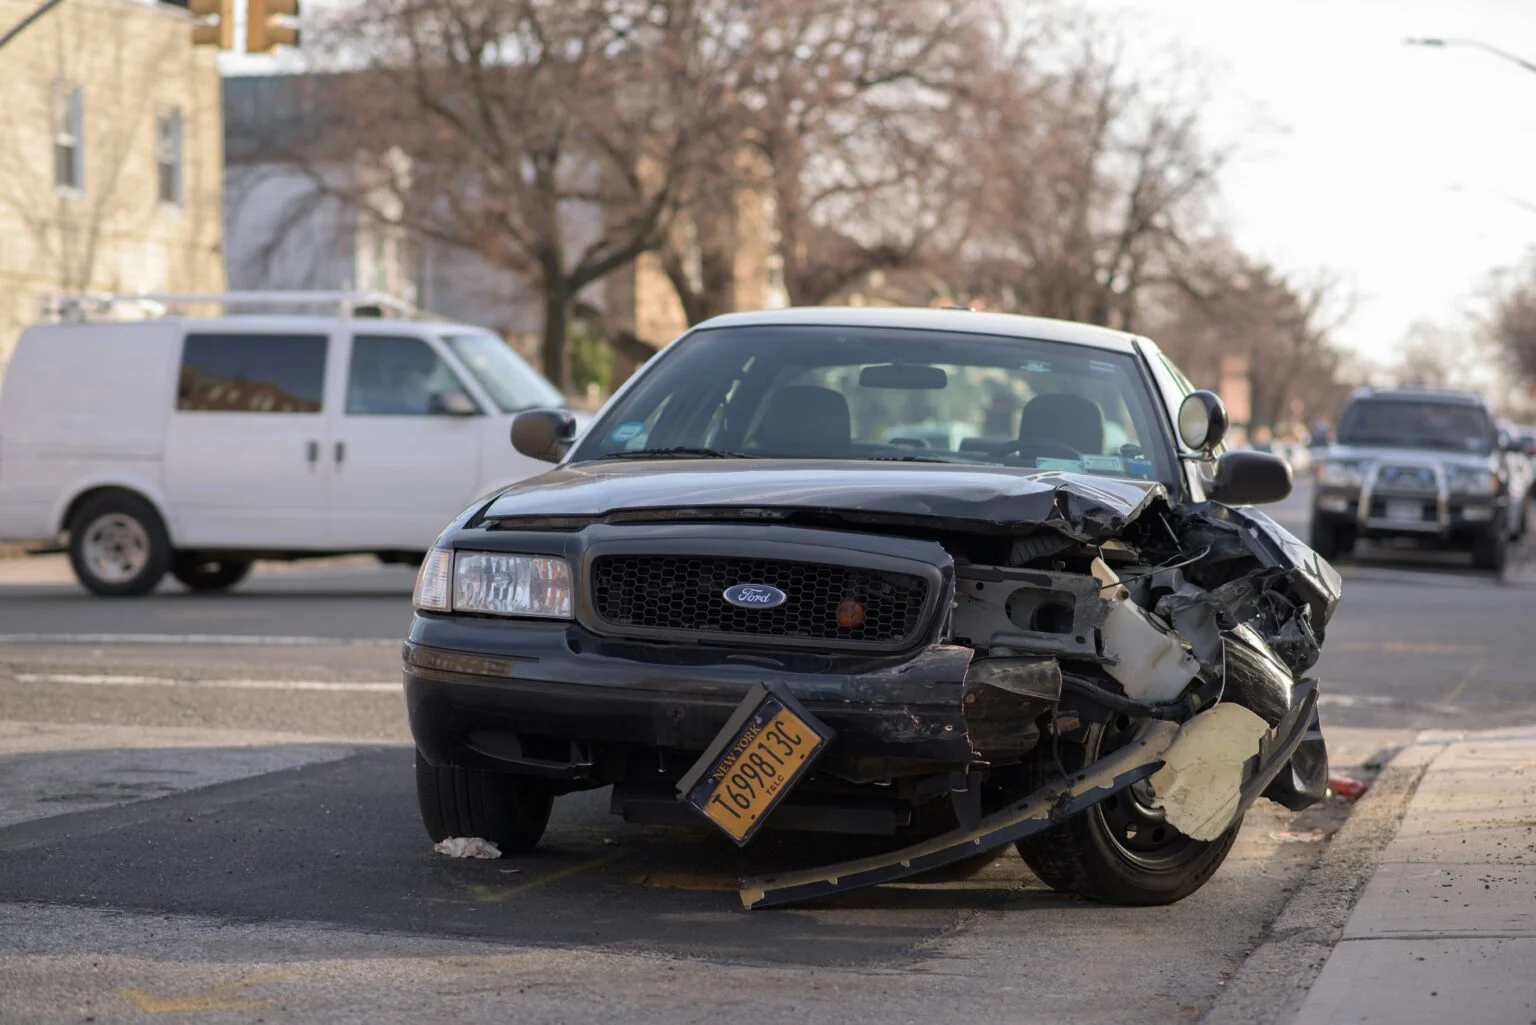
If an uninsured driver hits you in Georgia, your own uninsured motorist (UM) coverage is often the main way to get paid for your injuries. Georgia’s UM statute, O.C.G.A. § 33-7-11, treats a driver as “uninsured” not only when there is no insurance at all, but also when the driver’s coverage is too low, the driver’s insurer has denied coverage or is insolvent, or the driver cannot be identified.
You can also sue the uninsured driver directly, but many uninsured drivers have few assets to collect from. How much protection you have depends on the UM limits and type of coverage on your policy, and on following Georgia’s notice and service rules.
Key Takeaways
- UM coverage on your own auto policy can pay when the at-fault driver has no insurance, not enough insurance, or can’t be identified.
- Georgia’s default is “add-on” UM coverage, which pays on top of the other driver’s liability insurance, unless you chose “reduced-by” coverage in writing.
- A hit-and-run UM claim requires physical contact or an independent eyewitness, plus a police report.
- If you sue, your UM insurer must be properly served within the two-year statute of limitations (O.C.G.A. § 9-3-33).
- Your own insurer may dispute fault or the value of your claim, because it is the one paying.
First Steps After a Crash with an Uninsured Driver
Call the police. Georgia law requires reporting a crash that causes injury, death or apparent property damage of $500 or more (O.C.G.A. § 40-6-273). A police report documents the crash and may note insurance information. Our guide to Georgia crash report codes explains how to read it.
Get the other driver’s information. Georgia law requires drivers in a crash to give their name, address and vehicle registration number, and to show their license on request (O.C.G.A. § 40-6-270). Photograph the driver’s license, plate, vehicle and any insurance card. If the driver says the insurance “lapsed” or offers to pay cash, write that down.
Get witness information. Names and phone numbers of anyone who saw the crash can be critical, especially in a hit-and-run.
Get medical care. See a doctor promptly, even if your injuries seem minor, and follow the treatment plan. Keep every bill and record, and a journal of how your injuries affect daily life.
Notify your insurer. Report the crash to your own insurance company promptly. Many policies have notice requirements for UM claims.
How Uninsured Motorist Coverage Works in Georgia
UM coverage is part of your own auto policy. Under Georgia law, it generally protects you and resident relatives in your household, and it can apply whether you were driving, riding as a passenger, walking or biking, depending on the policy’s wording.
Required unless rejected. Georgia requires insurers to include UM coverage unless a named insured rejects it in writing (O.C.G.A. § 33-7-11(a)(3)). Unless you affirmatively chose lower limits, your UM limits generally match your bodily injury liability limits.
Add-on vs. reduced-by. With add-on (excess) coverage, your UM limits are available on top of the at-fault driver’s liability insurance, up to your actual damages. With reduced-by coverage, your UM limits are reduced by the other driver’s coverage. Add-on is the default unless you selected reduced-by in writing.
Why it matters. Georgia’s minimum liability limits are $25,000 per person and $50,000 per crash for bodily injury. A serious injury can quickly exceed those amounts. The Insurance Research Council estimated that about 19% of Georgia motorists were uninsured in 2023.
More than one policy. You may be able to recover under more than one UM policy, for example your own and a household member’s policy. Whether coverage can be combined depends heavily on the policy language. Our Georgia UM coverage guide explains these rules in more detail.
Hit-and-Run Crashes
When the at-fault driver cannot be identified, Georgia’s UM statute sets extra requirements (O.C.G.A. § 33-7-11(b)(2)):
- There must have been actual physical contact between the unknown vehicle and you or your property, or your account must be corroborated by an eyewitness other than you.
- The crash must be reported to police as required by O.C.G.A. § 40-6-273.
If a lawsuit is needed, it can be filed against the unknown driver as “John Doe,” with a copy served on your UM insurer.
Suing the Uninsured Driver
You can file a personal injury lawsuit against the uninsured driver. In Georgia, you generally have two years from the crash to do so (O.C.G.A. § 9-3-33). See our guide to Georgia personal injury deadlines.
Two rules matter here:
- Serve your UM insurer. If you sue, your UM insurer must be served with the lawsuit as though it were a named defendant, and it can take part in the case in its own name or the driver’s name (O.C.G.A. § 33-7-11(d)). Missing proper service within the limitations period can put UM benefits at risk.
- Underinsured drivers and limited releases. If the at-fault driver has some insurance and the insurer offers its full policy limits, Georgia law lets you accept and sign a limited release that preserves your UM claim (O.C.G.A. § 33-24-41.1). Signing the wrong kind of release can create problems, so get advice first.
A judgment against an uninsured driver can be enforced through legal collection methods such as garnishment, subject to limits under Georgia and federal law. In practice, many uninsured drivers have limited assets, which is why UM coverage is often the primary source of recovery.
When Your Own Insurer Is on the Other Side
Because your UM insurer is the one paying, its interests on the value of your claim are opposite to yours. It may ask for a recorded statement, broad medical authorizations or an examination by a doctor it chooses, and it may make an early offer before the full extent of your injuries is known. Our article on insurance lowball tactics covers what to watch for.
Georgia has a specific penalty for UM insurers that refuse to pay in bad faith. Under O.C.G.A. § 33-7-11(j), if your insurer refuses to pay a covered UM loss within 60 days after a demand and the refusal is found to be in bad faith, it can be liable for up to 25% of the recovery or $25,000, whichever is greater, plus reasonable attorney’s fees. Bad faith is hard to prove, and an insurer with a reasonable basis to dispute a claim generally is not acting in bad faith.
What You May Recover
Through UM benefits, a lawsuit or both, damages can include medical expenses, lost wages and earning capacity, pain and suffering, and property damage such as vehicle repair, towing and a rental car. Georgia law does not allow you to be paid twice for the same loss, so recoveries from different sources are coordinated. For claims arising on or after April 21, 2025, Georgia’s tort reform law (SB 68) may also affect how medical expenses are proven (O.C.G.A. § 51-12-1.1). Learn more on our uninsured and underinsured motorist page.
Frequently Asked Questions
Will My Insurance Pay If an Uninsured Driver Hits Me?
It may, if you have UM coverage. Georgia insurers must include UM coverage unless a named insured rejected it in writing. Check your declarations page for your UM limits and whether the coverage is “added on” or “reduced by.”
Can I Sue an Uninsured Driver in Georgia?
Yes. You generally have two years from the crash to file. If you sue, your UM insurer must be properly served within that time. Collecting from an uninsured driver can be difficult, so UM coverage is often the main source of payment.
Does UM Coverage Apply to a Hit-and-Run?
It can. Georgia requires either physical contact with the unknown vehicle or an eyewitness other than you who corroborates your account, and the crash must be reported to police.
What If the At-Fault Driver Has Insurance but Not Enough?
Georgia’s UM statute also covers underinsured drivers. If the driver’s insurer offers its full limits, you may be able to accept and sign a limited release that protects your UM claim under O.C.G.A. § 33-24-41.1.
If you were hurt by an uninsured, underinsured or hit-and-run driver, talk with The Gunn Law Group about your coverage and options. The consultation is free and there is no obligation, and there is no attorney fee unless we recover for you. Call 888-BIG-GUNN (888-244-4866). Hablamos español.