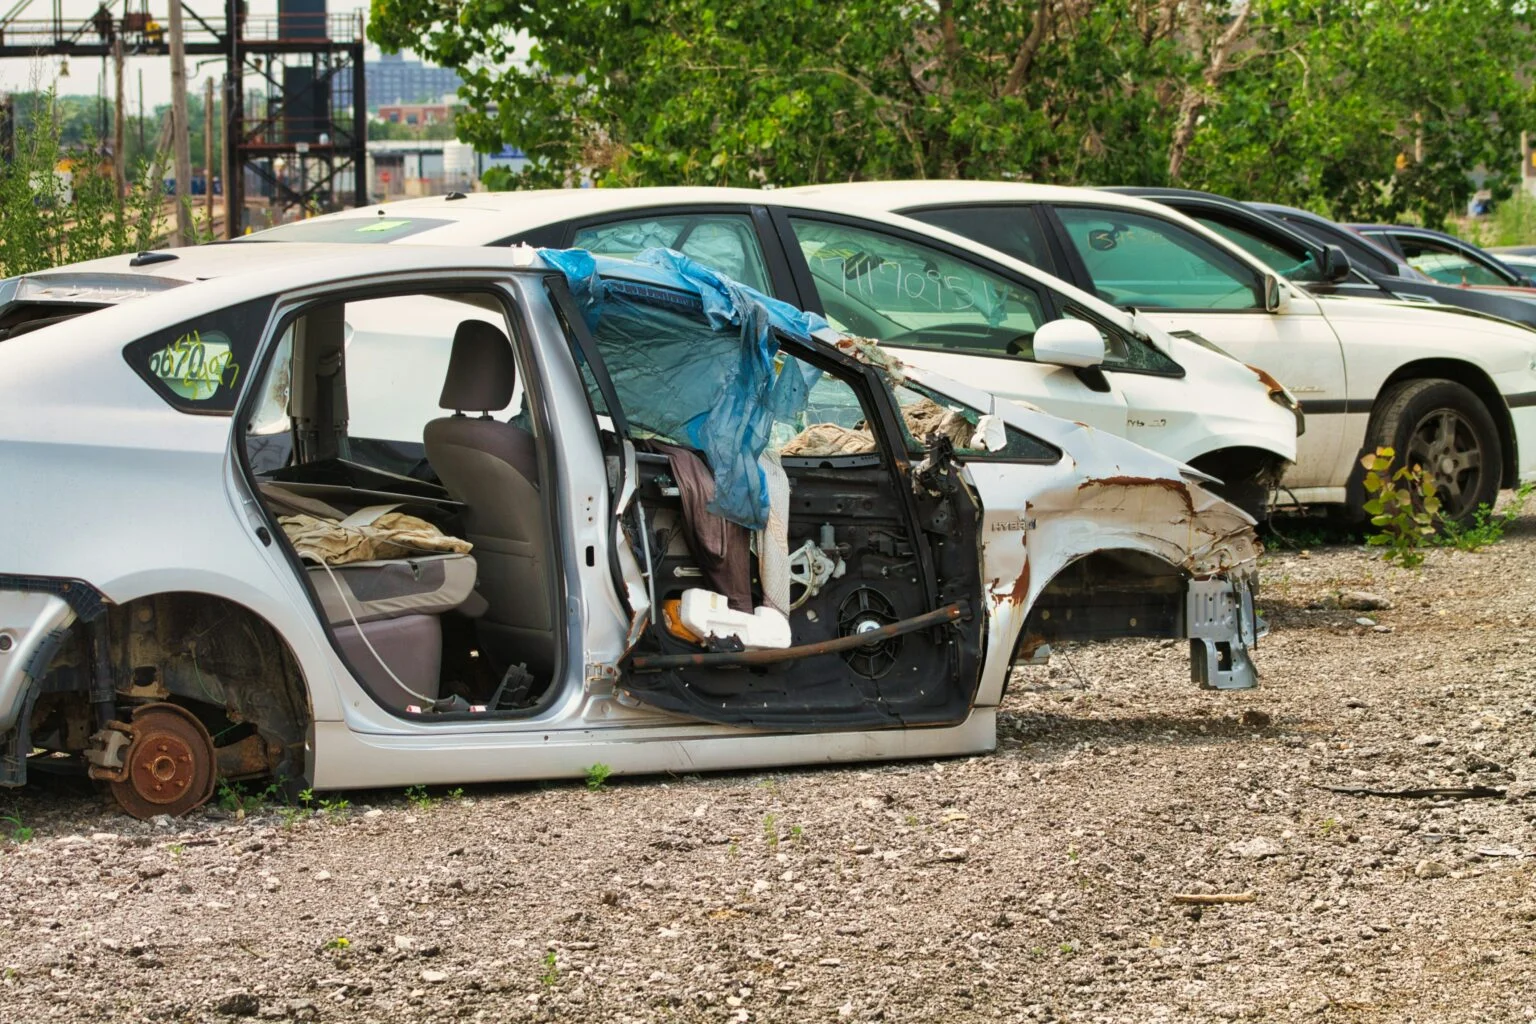
When your car is totaled in Georgia, the insurance company pays its actual cash value: what the car was worth right before the crash, based on similar cars for sale near you. That is not what you owe on the loan and not what a newer car costs.
The first offer is often too low because the valuation report has errors. You can challenge it with your own evidence, and you should keep the car claim from rushing decisions about your injury claim.
Key Takeaways
- A total loss payout is based on actual cash value, usually taken from a valuation report of comparable cars.
- When your own insurer pays, a Georgia regulation sets valuation rules and requires applicable taxes and fees to be included.
- Most low offers come from data errors you can find and correct in the valuation report.
- Your lender is paid first; GAP coverage may cover a shortfall on the loan.
- Keep the car claim separate from your injury claim, and read every release before you sign.
What a Total Loss Offer Is Based On
Actual cash value (ACV) is the market value of your car the moment before the wreck. Insurers usually get it from a valuation report that compares your car with similar vehicles for sale in your area, then adjusts for mileage, options and condition.
- If your own insurer pays (under your collision coverage, for example), a Georgia insurance regulation sets the rules. The insurer must value your car using comparable vehicles in your local market (generally within 50 miles, then up to 100 miles if none are available), dealer quotes, or an approved valuation database, and the settlement must include applicable taxes, license fees and transfer fees, limited to what would have been paid on your car (Ga. Comp. R. & Regs. r. 120-2-52-.06).
- Sales tax: in 2022 the Georgia Insurance Commissioner directed insurers to pay the actual taxes you will owe when you replace the car, not a smaller amount (Directive 22-EX-2).
- If the at-fault driver’s insurer pays, the claim is based on Georgia negligence law: you are owed the car’s fair market value before the crash, plus other losses such as a rental car or loss of use. The regulation above is written for claims against your own insurer, but asking for the same breakdown is still a good idea.
Why Total Loss Offers Come in Low
Most low offers come from data problems, and each one can move the number by hundreds or thousands of dollars:
- The wrong trim level, or missing packages such as technology, safety or sport packages
- Mileage that was estimated or entered incorrectly
- Condition graded too low without photos or proof
- “Comparable” cars that are a different trim, have much higher mileage, or are listed far from your area
- Taxes, title fees or transfer costs left out of the calculation
- Recent work ignored, such as new tires, brakes or a replaced transmission, and upgrades you can document
Our guide to insurance lowball tactics covers other ways adjusters try to shrink claims.
What to Do Before You Accept Anything
- Ask for the full valuation report in writing, including every comparable vehicle and every adjustment. If the insurer will not share it, that is a red flag.
- Check it line by line: VIN, year, trim, mileage, options, condition and each deduction.
- Build your own comparable list. Find 3 to 6 listings for the same year, make, model and trim with similar mileage in your area. Save screenshots with the date and price.
- Gather proof of value: service records, receipts for recent repairs and upgrades, and photos of the car from before the wreck.
- Ask what is included: taxes, title and registration fees, and any rental or loss of use payment.
- Send a written counteroffer with your comparables and receipts attached. Keep it factual.
- Read every release before you sign. A property damage release should cover the car only. Some paperwork is written broadly enough to affect other claims.
If You Still Owe Money on the Car
Your lender (the lienholder) is paid first from the total loss check. If the payout is less than your loan balance, the difference is the “gap.” GAP coverage may pay that difference if you bought it. Either way, the highest accurate valuation matters, because it directly lowers what you are left owing.
Rental Car and Getting Around
A total loss can leave you without a way to get to work or to your doctor. Ask right away about rental coverage or loss of use, and keep receipts for reasonable transportation costs. If your car was repaired instead of totaled, you may have a different claim for the value it lost, often called diminished value.
Keep the Car Claim Separate from Your Injury Claim
The car claim moves fast. The injury claim depends on your treatment, which takes time. Insurers like it when people settle both quickly.
- Get checked out and follow through with treatment, even if symptoms show up days later.
- Do not let a quick car payment push you into a recorded statement or an early injury settlement.
- Fault matters to both claims. Georgia uses modified comparative negligence: if you are less than 50% at fault, your recovery is reduced by your share, and at 50% or more you recover nothing (O.C.G.A. § 51-12-33). Our guide to what a Georgia car accident case is worth explains how fault affects value.
- Deadlines differ. Most injury lawsuits must be filed within two years, and property damage claims generally within four years (O.C.G.A. §§ 9-3-33, 9-3-31). See our guide to Georgia personal injury deadlines.
When an insurer tries to rush you, we slow the process down and tighten it up. We challenge the valuation, find what is missing, identify every available policy, and make sure the property claim does not undercut your health, your treatment or the rest of your car accident claim.
Frequently Asked Questions
How Is a Totaled Car Valued in Georgia?
Insurers pay actual cash value, which is what the car was worth right before the crash based on comparable vehicles in your local market, adjusted for mileage, options and condition.
Can I Negotiate a Total Loss Offer?
Yes. Ask for the valuation report, correct any errors, and send your own comparable listings and receipts. Documented corrections give the adjuster a concrete reason to revise the number.
Does the Insurance Company Have to Pay Sales Tax on a Totaled Car in Georgia?
When your own insurer pays a total loss, Georgia rules require the settlement to include applicable taxes and fees, and a 2022 directive told insurers to pay the actual taxes owed on the replacement. Ask the adjuster to show the tax amount in writing.
Should I Settle My Car Claim Before My Injury Claim?
You can resolve the car claim first, but read every release carefully so it covers only the vehicle, and do not let the property claim rush decisions about your medical care or your injury claim.
If your car was totaled and the offer feels wrong while you are trying to heal, you do not have to handle it alone. The Gunn Law Group offers a free, no-obligation consultation, and there is no fee unless we recover for you. Call 888-BIG-GUNN (888-244-4866) or request a free case review.